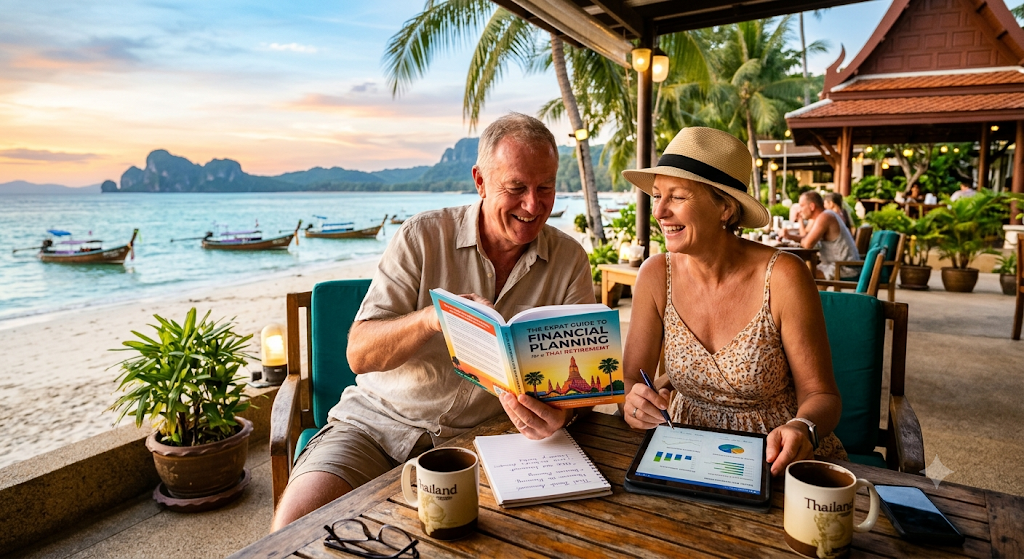
An estimated 100,000 Western expats currently reside in Thailand as retirees, drawn by the combination of modern infrastructure and a highly favourable cost of living. In the 2025 InterNations Expat Insider survey, Thailand ranked as the fourth best country globally for expatriates, specifically praised for its robust quality of life and exceptional affordability. However, moving overseas requires far more than just packing your bags and buying a plane ticket. It demands a highly strategic approach to personal finance, healthcare planning, and legal compliance. Understanding the intricacies of international finance can be the difference between a stressful transition and a truly relaxing golden age.
The Economics of Relocation
Relocating to a more affordable area is a proven strategy to maximise savings. We can see this clearly in domestic trends, as many people are escaping inflated housing markets and joining the urban exodus of Americans fleeing coastal cities in droves to lower their everyday living costs. Relocating abroad offers a similar, and often much more dramatic, financial advantage for retirees looking to make their pensions stretch further.
Financial experts generally advise budgeting between $1,500 and $2,500 per month to maintain a highly comfortable, amenity-rich lifestyle in Thailand. To put this into perspective, recent comparative data confirms that the overall cost of living in the United States is roughly 91.5% higher than in Thailand, excluding rent. Rent prices alone in the US are a staggering 161.1% higher. This massive discrepancy allows your retirement funds to stretch considerably further while affording luxuries that might be out of reach back home.
Navigating Visa Minimums and Medical Coverage
Legal residency in Southeast Asia comes with strict, government-regulated financial prerequisites. For instance, to successfully qualify for the Thai Non-Immigrant O-A retirement Visa, applicants must be at least 50 years old and clearly prove their financial stability. This is accomplished by maintaining a Thai bank deposit of at least 800,000 THB (approximately $22,000 USD) or proving a consistent monthly pension of 65,000 THB.
Alongside bank deposits, the Thai government mandates that long-stay residents hold a compliant health insurance policy. This policy must provide a minimum of 3,000,000 THB (roughly $100,000 USD) in overall medical coverage per policy year. Depending on age and medical history, expats should plan to allocate between $600 and $1,500 annually for private health premiums to satisfy these continuous renewal requirements. Fortunately, the healthcare system is excellent. Thailand boasts approximately 65 Joint Commission International accredited medical facilities, offering world-class care at a fraction of Western costs. Furthermore, many of these hospitals employ internationally trained physicians who speak fluent English, ensuring clear communication and peace of mind during medical consultations or emergencies.
Tax Regulations and Managing Remittances
Another critical component of financial planning is understanding local tax laws. A sweeping change to the Thai Revenue Code enacted on January 1, 2024, dictates that tax residents are now taxed on all foreign-sourced income remitted into the country. A tax resident is formally defined as anyone living in Thailand for 180 days or more annually. This represents a significant shift from previous decades, where the regulatory environment was largely hands-off regarding offshore wealth.
Previously, expats could legally avoid local income tax by remitting foreign earnings in a calendar year after they were earned. This loophole has now been completely closed for pensions, dividends, and interest. Financial planners are closely monitoring proposed legislative drafts from 2025, which suggest a possible exemption window allowing foreign income to be remitted tax-free only if held offshore for two full calendar years.
A Checklist for a Smooth Financial Transition
Preparing your finances for a move to Southeast Asia requires a highly structured approach. Before you book your flights, consider completing the following essential tasks to protect your assets:
- Establish a Thai bank account early to meet the mandatory deposit thresholds for your initial application.
- Secure an official Thai Tax Identification Number to ensure you remain compliant with the updated 2024 revenue codes.
- Audit your international remittance schedules before transferring offshore retirement funds to avoid costly tax penalties.
- Familiarise yourself with the government IMMO-Online portal, as mandatory 90-day address reporting for retirees is now processed almost entirely digitally.
Retiring in Southeast Asia offers a brilliant blend of modern infrastructure, cultural richness, and financial efficiency. By carefully evaluating your cost of living, understanding visa thresholds, and keeping up with the latest tax regulations, you can protect your hard-earned wealth. Proper planning ensures that your international retirement remains a relaxing, financially secure chapter of your life. Seeking guidance from qualified international financial advisors before taking the leap is always a sensible final step.